

Every study of great founders is written backwards. It starts with the companies that succeeded, traces the people who built them, and reports what they had in common. While the conclusions are usually sound, they cannot escape survival, which determines who is in the sample before counting begins.
Our own most recent attempt was no different. The Anatomy of Greatness, published in January this year, mapped nineteen shared characteristics across 1,629 unicorn companies and 3,512 founders. This was also, by construction, a study of people who had already won.
Antler’s data begins earlier. We record who a founder is at the point we invest, often before there is revenue, a financing history, or a market view on whether the company will matter. Across 4,200 funded founders in 26 markets, this is a picture of the founder before success exists to flatter it. Most of it confirms what investors already believe. One part doesn’t.
So let’s dig in.
The part you would have guessed
In 2025, 136,000 people applied to build with Antler and 394 were funded, roughly one in 346. The profile looks much as you would expect.
They are experienced, with an average of eleven years of full-time work behind them. Two in three had already founded a company, 68% of the 2,675 who recorded a founding history, against 40% of the confirmed unicorn founders in our January study. They are older than the stereotype suggests. The average age at investment is 34, the most common bracket is 30 to 34, and around one in twenty is under 25. One in six came from a globally recognised employer, among them Google, Amazon, McKinsey, Grab and Klarna. Just over half hold a postgraduate qualification.
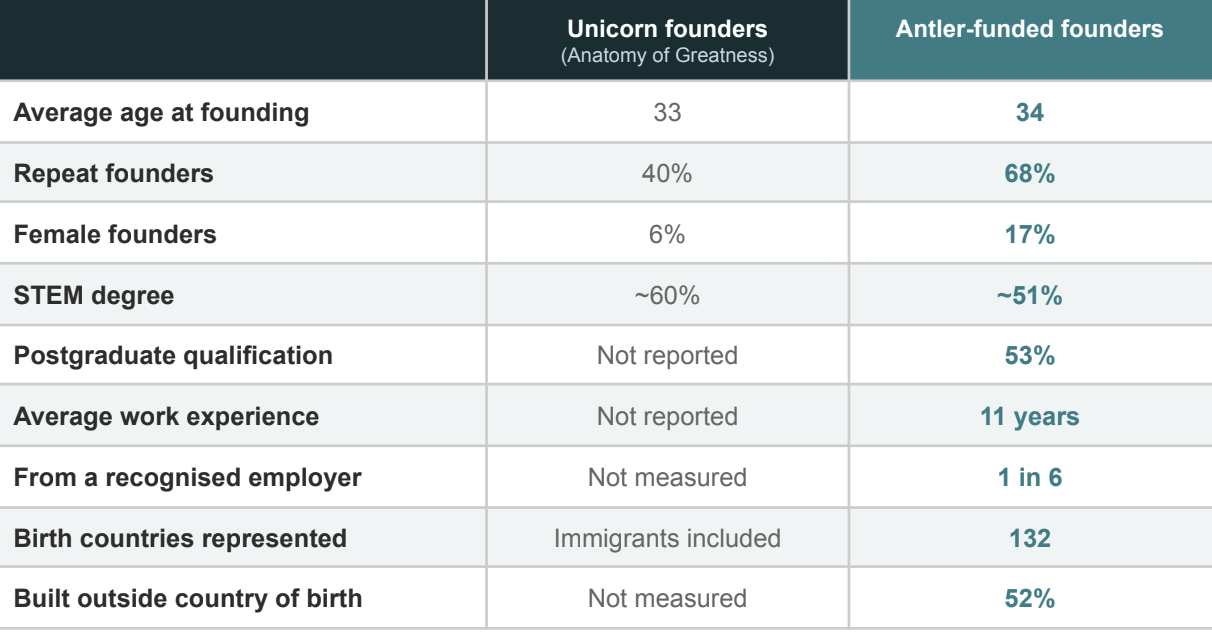
None of it is especially surprising. Experience, a repeat attempt, a recognisable employer on the CV: this is the founder hindsight studies have described for years.
The part hindsight cannot see
It does not end there. The consensus profile carries a geographic blind spot, and behind it is a founder with no fixed address.
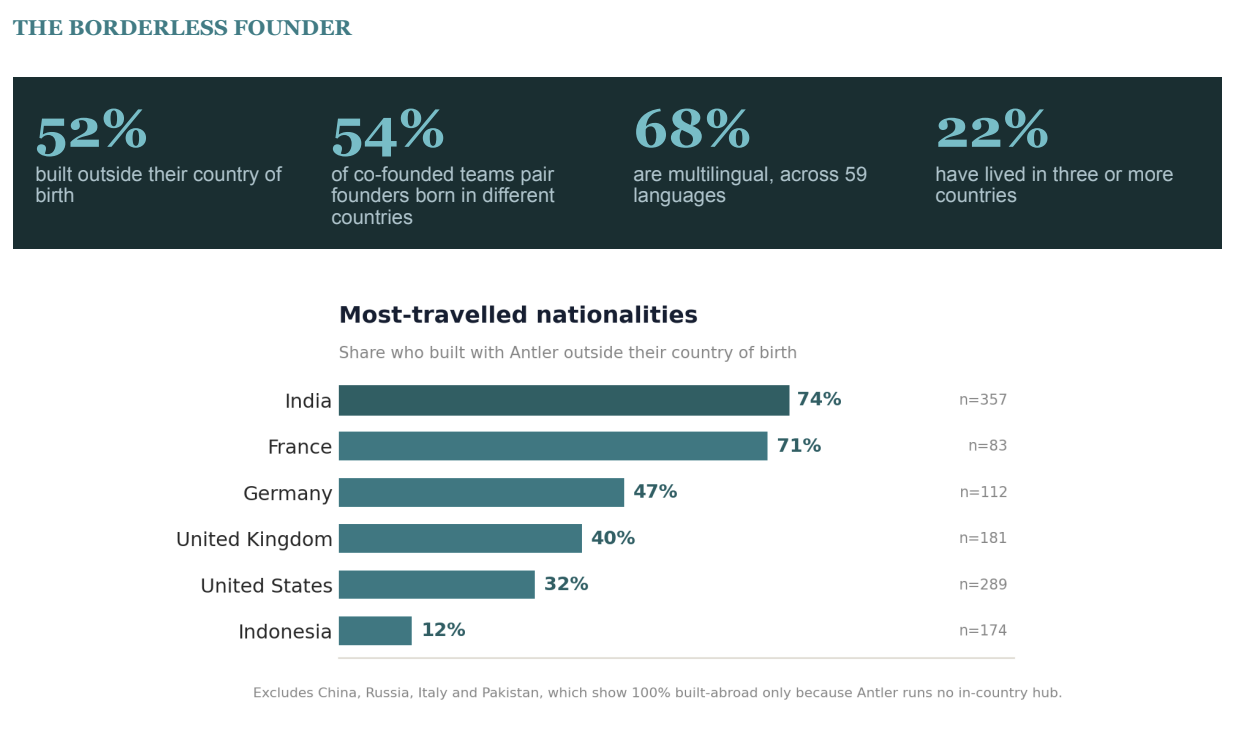
The founders who recorded a birth country were born in 132 different ones. No single nationality accounts for more than about one in eight of the total. Even the largest group, Indian-born founders, appears across twelve of our fourteen hubs rather than clustering in one geography.
Then there is the movement. Among the 925 co-founded companies with birth-country data for at least two founders, 54% pair people born in different countries. More than half of those teams are international from formation, not only after they scale.
52% of funded founders built with Antler in a country other than the one they were born in. Two in three speak more than one language, 59 languages across the base, and one in five has lived in three or more countries.
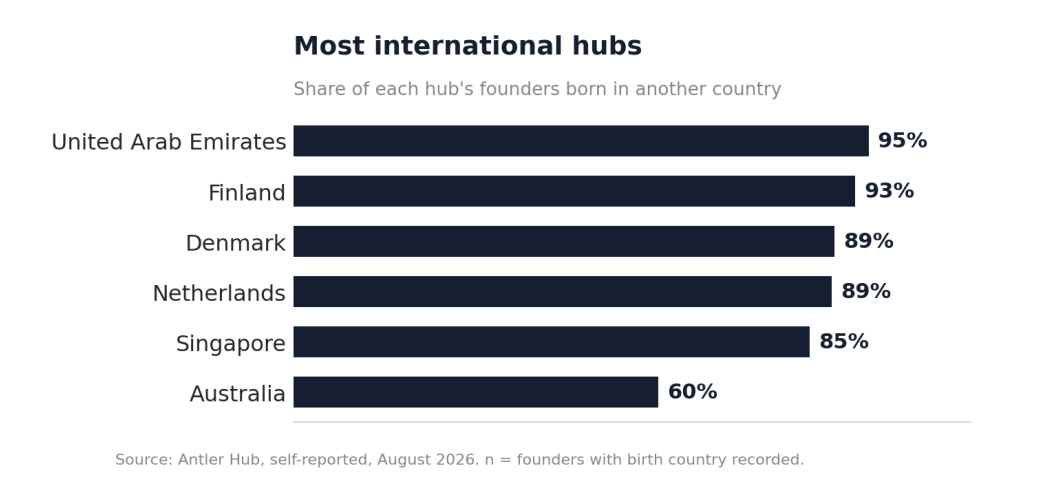
A hindsight study cannot recover any of this. By the time a company is a recognised winner, its founder’s location has usually been rewritten by relocation, and the founding geography collapses into a headquarters address. We see the founder at formation, in the country where they actually started, which is why the pattern is visible to us and absent from the public record.
Why it reads differently from here
The familiar traits, the experience and the pedigree, are visible to everyone and priced accordingly. The borderless ones are visible only at formation. One is a description of the founder. The other is a question of who is in the room.
Every earlier attempt to describe the winning founder had to wait for the winning. This one did not. Whether founders like these ultimately outperform is a question for the next decade, not this paper. What we can say now is what the founder population looked like before the outcome was known.
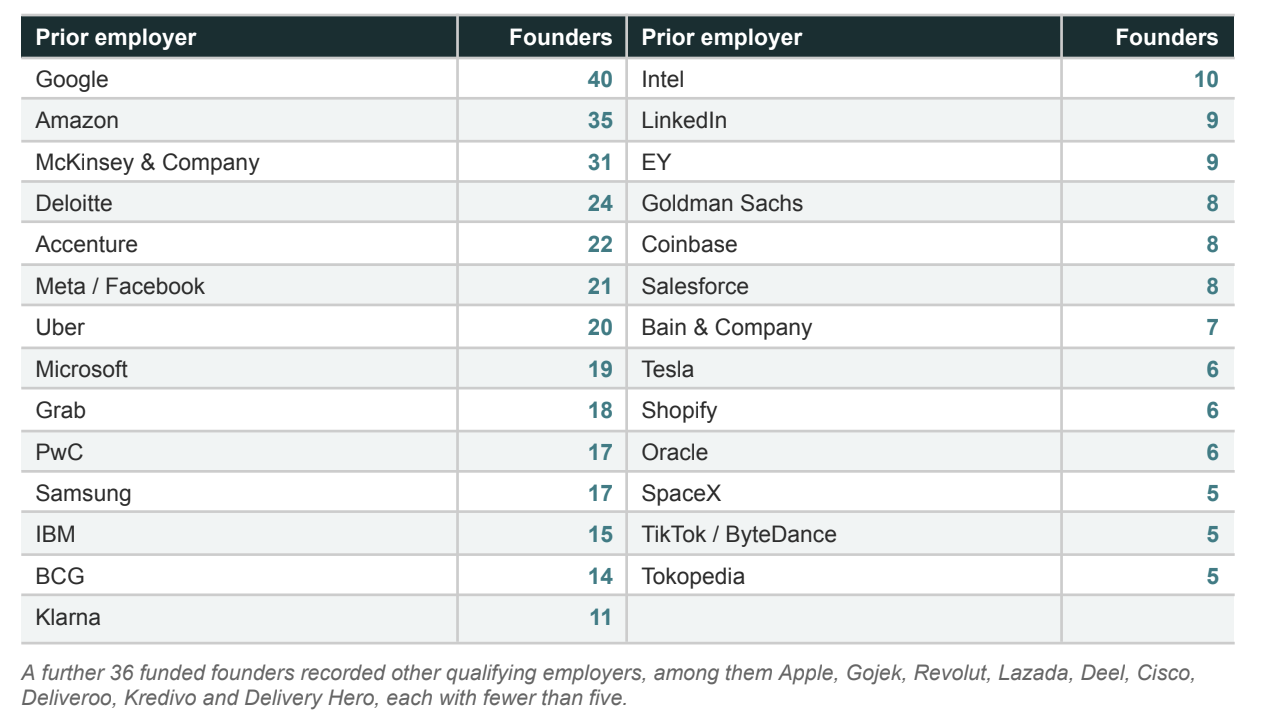
APPENDIX: PRIOR EMPLOYERS
Funded founders who recorded working at a globally recognised employer, by employer. Counts are self-reported and matched by employer name, so subsidiaries and informal names may be undercounted. The definition of a recognised employer is given under Data and Disclosure.
ABOUT ANTLER INTELLIGENCE
Antler is one of the most active early-stage venture firms globally, with US$1.3B+ AUM, operations across 26 cities, and a portfolio of nearly 2,000 companies spanning every major technology market. Antler Intelligence is our research and market insight function designed for an LP audience. The views expressed here are based on proprietary portfolio data and represent our analytical perspective on market trends. They do not constitute investment advice.
DATA AND DISCLOSURE
Source. Self-reported by founders via Antler Hub, Antler’s proprietary data platform, as of August 2026. Where a founder did not record a field, they are excluded from that field’s calculation; every percentage is against the founders with the field recorded, not the full base.
Base. 4,202 funded founders, aggregated across all Antler early-stage programmes globally. “Markets” are the cities in which Antler operates (26); “hubs” are its investing entities or funds (14).
Coverage by field. Gender 82%, birth country 74%, founding history 64%, age 63%, work experience 63%, prior employers 63%, education 58%.
Self-reported versus enriched. Self-reported data takes precedence. Where public professional-profile data is used to fill gaps, it is labelled. The figures in this piece are self-reported.
Recognised employer. A large public company (market capitalisation above $10 billion), a company holding unicorn or decacorn status at the time of employment, or a leading global firm in management consulting, investment banking or audit. More than 70 organisations qualified.
STEM. The STEM share is classification-dependent (how fields of study are grouped) and is reported here at about half. Mobility. Build location is the country of the Antler programme a founder joined, compared with their self-reported country of birth. The most-travelled ranking excludes China, Russia, Italy and Pakistan, which show 100% built-abroad only because Antler runs no in-country hub for them.
Cross-border teams. Measured across the 925 co-founded companies where a birth country is recorded for at least two founders.
Gender. The 17% female figure is a pipeline measure and is not directly comparable with the 6% recorded among confirmed unicorn founders, which is an outcome measure.
Comparison. Unicorn-founder figures are from The Anatomy of Greatness (Antler, January 2026), a study of 1,629 unicorn companies and 3,512 founders built on public data. The two datasets measure different points in a company’s life and are not directly comparable.
This document is for information only. Nothing here is investment advice, nor an offer or solicitation to invest in any Antler fund. Figures are self-reported and unaudited, reflect the founder population at the date shown, and are not a prediction of returns.
ANTLER RESIDENCY —LAUNCH YOUR STARTUP
Antler backs exceptional founders to go further, faster.